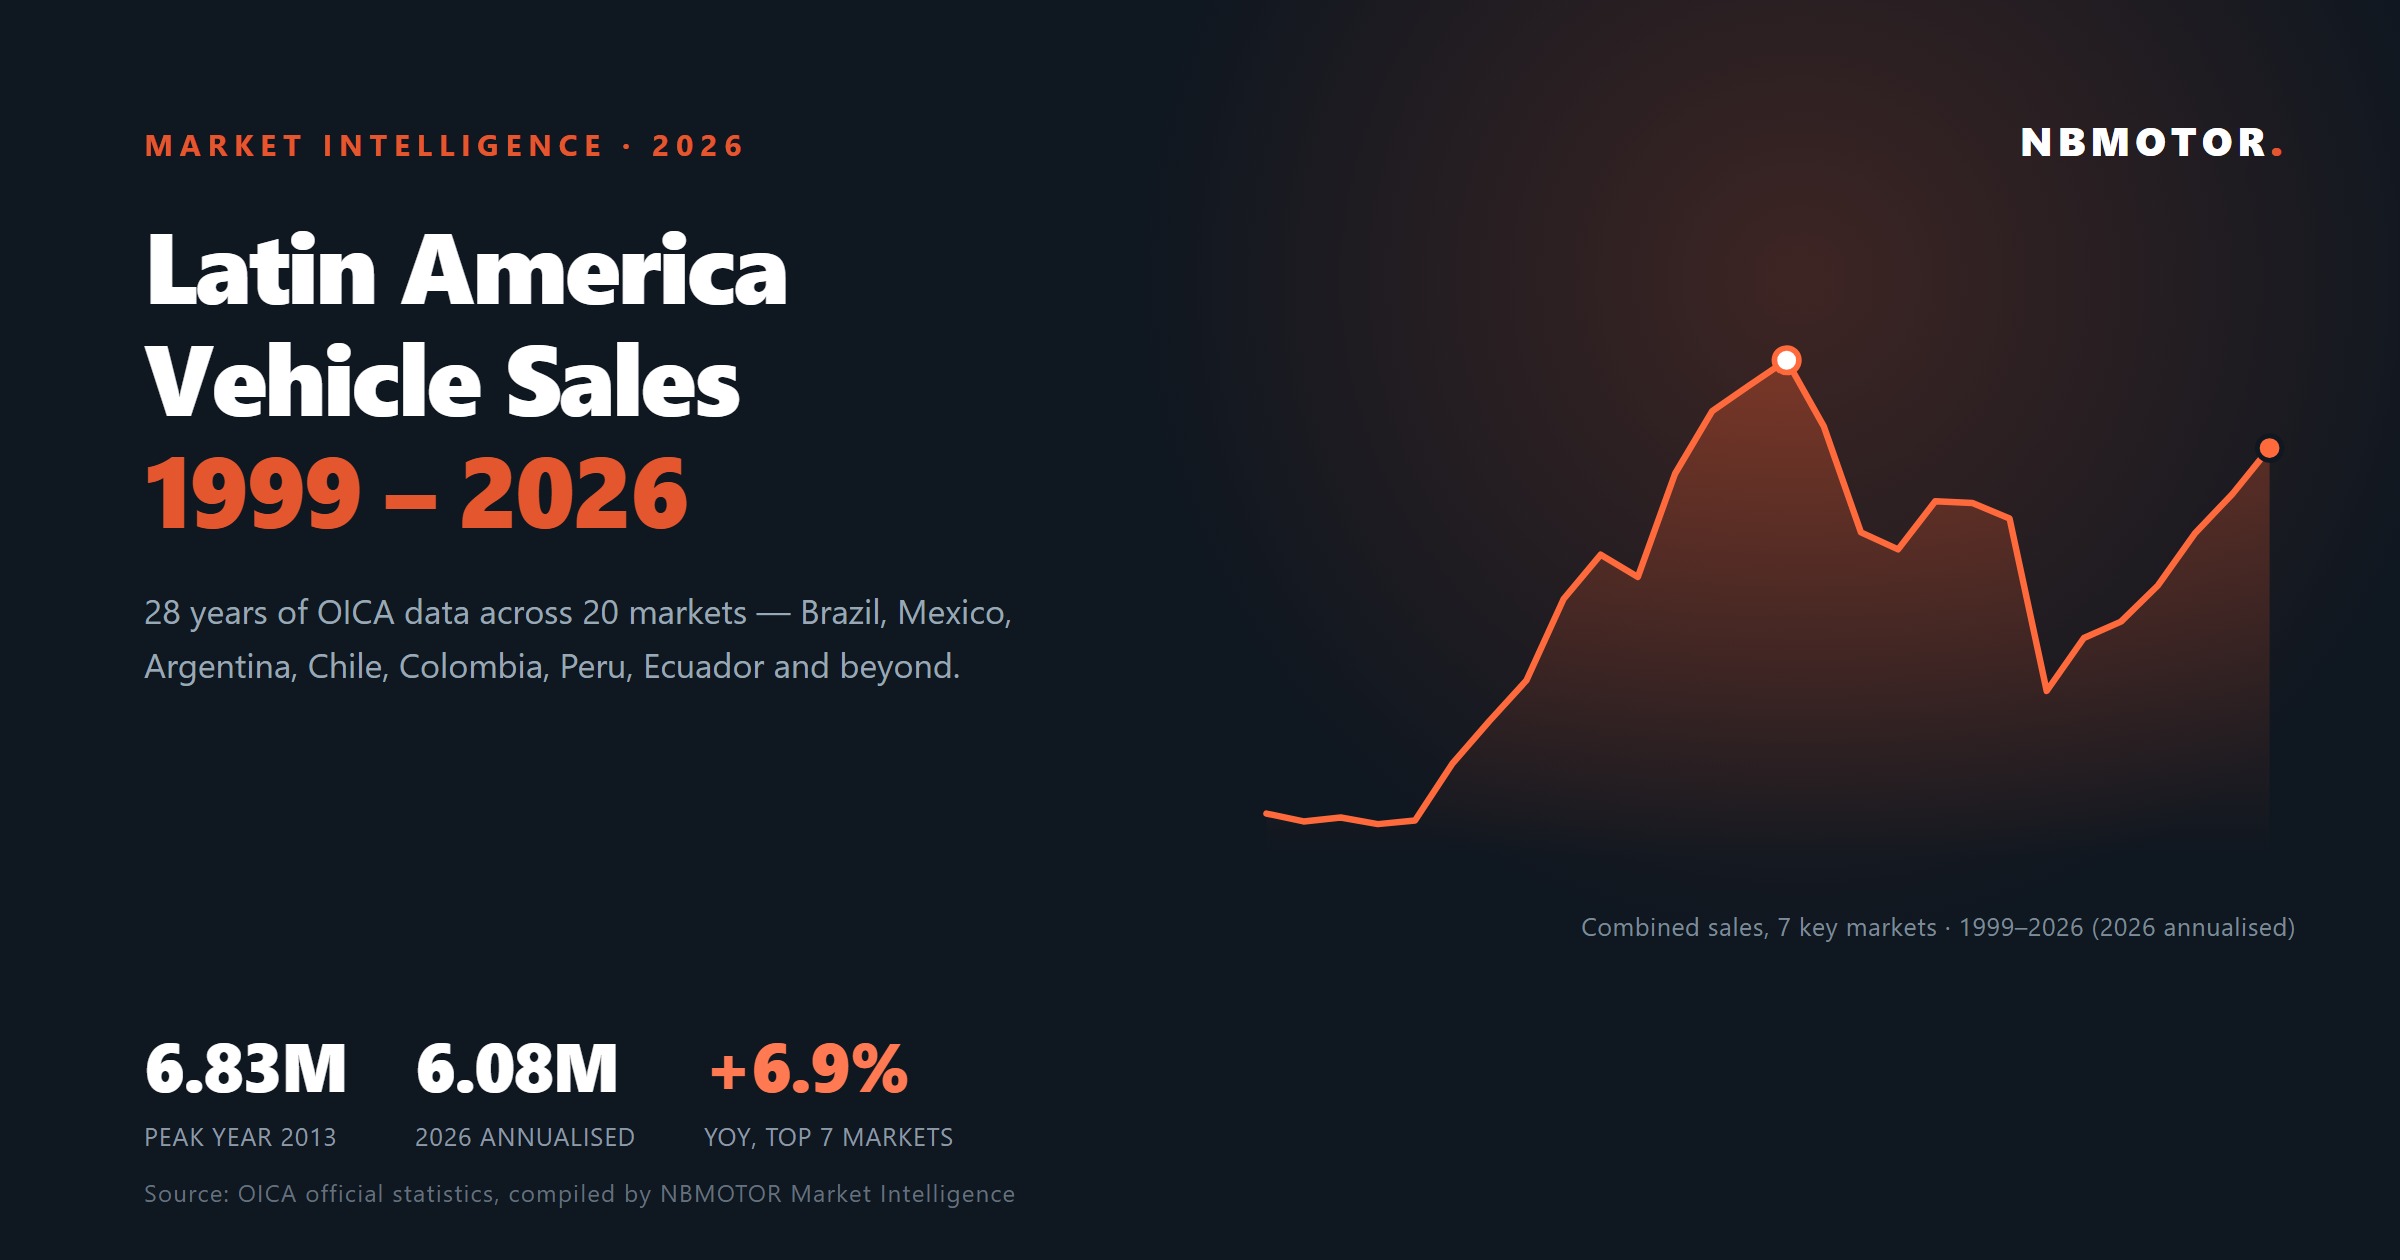
Latin America sold 6.08 million vehicles in 2026 on an annualised basis — up 6.9% year on year across the seven largest markets, and still 11% below the 2013 all-time peak of 6.83 million. That gap between the peak and today is the single most useful number for anyone selling into the region’s aftermarket: the vehicle fleet kept growing while new-car sales did not, which means the average age of the car parc is rising.
We pulled 28 years of OICA data for 20 Latin American markets and built the interactive chart below — from the 1999 starting point, through the 2013 boom, the 2015–2016 collapse, the 2020 pandemic trough (3.99 million) and the current recovery.
| Combined sales, 7 key markets | 2.94 million (1999) → 6.83 million (2013 peak) → 5.68 million (2025) → 6.08 million (2026 annualised) |
|---|---|
| 2026 vs 2025 | +6.9% — Brazil, Mexico, Argentina, Chile, Colombia, Peru, Ecuador combined |
| Largest market 2026 | Brazil — 2.88 million units, +7.0% YoY; peak was 3.80 million in 2012 |
| Second market 2026 | Mexico — 1.53 million units, −2.5% YoY; peak was 1.65 million in 2016 |
| Fastest recovery | Peru +72% and Ecuador +65% YoY in 2026, off a low 2025 base |
| Deepest drawdown | Argentina — 963,917 units (2013) down to 395,562 (2022), now 581,000 |
| Coverage | 20 Latin American markets, 1999–2026, passenger cars and commercial vehicles combined |
Two patterns in the data drive parts demand in the region, and neither is visible if you only look at the latest year.
First, the parc is ageing. Brazil and Argentina both ran five-year stretches of falling new-car sales (2014–2019 and 2018–2022). Vehicles that were not replaced stayed on the road. That is repair-and-replace demand: control arms, ball joints, tie rod ends, stabiliser links, shock absorbers — the parts that fail on a 10-year-old car, not a new one.
Second, the recovery is uneven, and that is where sourcing decisions get made. Mexico is flat to slightly down while Peru, Ecuador and Colombia grow double digits. A distributor covering several countries in one container needs a supplier who can mix fast-moving chassis references with slower, model-specific lines — and who can hold the catalogue data straight.
That is the part we handle: our chassis programme covers 95% of the US car parc with ACES and PIES data continuously maintained, so a Latin American distributor can check fitment against a VIN list before the container is loaded. Where a market needs its own brand, we run private label programmes through our two partner factories. For distributors also carrying engine-side lines, our timing system programme — chain kits, tensioners, guides, sprockets, VVT sprockets and oil control valves — covers 85% of the US parc and 94.5% of the Mexican parc, and our GP turbocharger line sits alongside it.
Want the underlying dataset — 20 markets × 28 years, with a source note on every single data point? Email marketing@nbmotor.com and we will send the workbook.
NBMOTOR supplies suspension, steering and drivetrain parts from Ningbo, China — chassis parts, timing system, GP turbochargers, rubber parts and thermal management, with ACES/PIES catalogue support and private label capability. If you are building a programme for Brazil, Mexico or the Andean markets, send us your vehicle list and we will come back with coverage and pricing.
Email: marketing@nbmotor.com · Tel: +86-574-86113256 · WhatsApp: +86-13586508027